My 22-year-old sister cut my $500 birthday dress to pieces because she was “anxious,” and
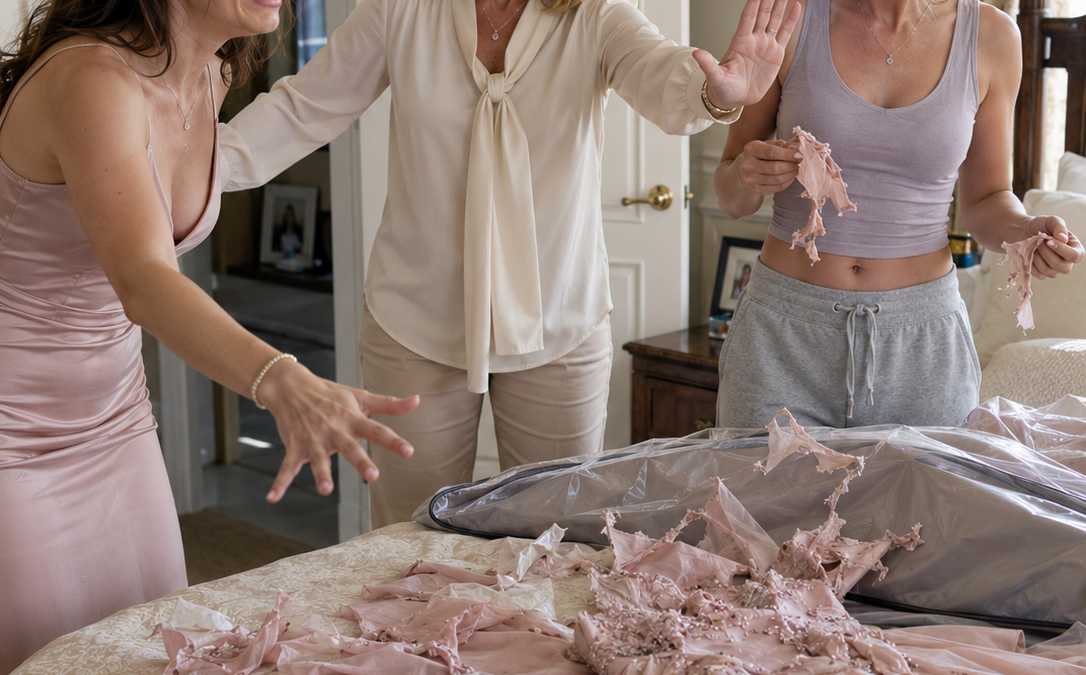
My 22-year-old sister cut my $500 birthday dress t…
My 22-year-old sister cut my $500 birthday dress to pieces because she was “anxious,” and my mother hissed, “Don’t overreact.” I swallowed it, left home, and spent three years building a life with my own lease and name. Then an $80,412 loan appeared, followed by a $42,000 HELOC on my parents’ house using my identity. My mother insisted, “You probably don’t remember signing it.” But my attorney uncovered a four-page power of attorney I never signed, and when a financial-crimes detective finally called, she warned me this family case needed proof nobody could dismiss…
(𝑷𝒍𝒆𝒂𝒔𝒆 𝒔𝒌𝒊𝒑 𝒕𝒉𝒆 𝒇𝒊𝒓𝒔𝒕 𝒑𝒂𝒓𝒕 𝒊𝒇 𝒚𝒐𝒖 𝒓𝒆𝒂𝒅 𝒊𝒕 𝒐𝒏 𝑭𝒂𝒄𝒆𝒃𝒐𝒐𝒌, 𝒂𝒏𝒅 𝒂𝒏𝒅 𝒕𝒂𝒑 𝒕𝒐 𝒕𝒉𝒆 𝒏𝒆𝒙𝒕 𝒑𝒂𝒈𝒆 𝒕𝒐 𝒓𝒆𝒂𝒅 𝒐𝒕𝒉𝒆𝒓 𝑪𝒉𝒂𝒑𝒕𝒆𝒓𝒔)
The police officer taking my statement had a coffee ring on his notepad and the exhausted voice of a man who had said the words “identity theft” so many times they no longer sounded frightening to him. They were frightening to me. My mouth kept catching on them, as if they belonged to somebody else’s life. “Ma’am, slow down,” he said. “Start with the envelope.” So I did. I told him about the yellow envelope Jess had carried into my office as though it might explode if she set it down too hard. I told him about the number printed at the bottom: $80,412. Then I gave him the loan origination date. Eighteen months after I had walked out of my parents’ house with two suitcases and a memory of ruined kitchen shears I had spent years trying not to revisit.
He wrote everything down, then explained that financial fraud wasn’t his department. I needed to file the report, let it be routed to the proper unit, and wait. “How long?” I asked. He gave me the answer nobody wants when their identity has apparently been used to borrow more money than they have ever seen sitting in one account. “Could be a few days. Could be a couple weeks.” Eleven minutes later, I was still sitting in my car outside the police station with both hands resting uselessly in my lap. I wasn’t crying. I was simply still, the way your body becomes still when the floor suddenly tilts and you have not yet figured out which direction you’re falling.
I wish I could say I saw it coming. I didn’t. I had spent three years creating a life that had nothing to do with the house I left behind. I lived in a studio over Meredith’s bakery, where cinnamon rolls scented my floorboards every morning. I worked at Whitmore & Cole, where Grant Whitmore, the principal who hired me, once said I drew as if I were “still deciding whether the building deserved to exist.” I had my own lease. My own paycheck. My own business card with my own name printed cleanly across it. I had blocked the phone numbers that needed blocking and convinced myself that leaving had been the ending.
It wasn’t.
The first truly strange discovery came nine days after that yellow envelope. Priya Nair, the attorney my firm’s HR director recommended, told me the first thing we needed was my complete credit report. Priya worked two floors above a dry cleaner and specialized in financial fraud recovery. She had the calm manner of someone who had already seen ten versions of your nightmare and knew panic would not improve any of them. When the report loaded, she turned her monitor toward me. “There’s a second account.”
I leaned closer.
“Opened four months after the first one,” she continued. “Home equity line of credit. First Union National. Forty-two thousand dollars. Secured against 118 Larksburg Court.”
My parents’ address.
“That doesn’t make sense,” I said. “A HELOC needs the homeowner’s signature. I don’t own that house.”
“You don’t,” Priya said. “But you’re listed as co-borrower and guarantor.”
She explained what that meant. Somebody had apparently used my income information and Social Security number to help qualify for a larger credit line than the property could support on its own.
I wanted it to be a bank error so badly that I almost convinced myself it had to be one. Databases make mistakes. Names get attached to the wrong accounts. Numbers get transposed. Surely my family could be cruel, manipulative, unfair, and exhausting without crossing into something criminal. I had spent years cataloging the worst things they had done to me, but this felt different. Bigger. Too deliberate.
Priya requested the loan file the next morning.
Three business days later, First Union sent forty-one pages.
Page six changed everything.
There was a power of attorney bearing my signature, dated fourteen months earlier.
I did remember signing a power of attorney once. My father had gone into Saint Agnes Medical Center for gallbladder surgery, developed an infection, and remained hospitalized for a week. I spent those days driving between the hospital and my studio, handling insurance paperwork because my mother had never been comfortable managing financial forms. The document I signed was narrow and specific. Medical decisions only. Effective during Dad’s hospitalization. Expiring upon discharge.
One page.
I remembered the tired notary at the UPS store stamping it and wishing me a good day.
The document Priya was showing me had four pages.
“This isn’t what I signed.”
My hands weren’t shaking yet. That came later. At first, there was only a strange cold clarity.
Priya met my eyes.
“I believe you.”
The relief lasted about half a second.
“But believing you isn’t evidence,” she continued. “We need someone who can prove it.”
That night, I called my mother.
Some old instinct in me still believed I could make the problem smaller by speaking gently. I thought if I explained everything without accusation, somebody would panic, admit what happened, and help me fix it privately. Quiet had been my family’s preferred currency for years, and apparently I still had some left to spend.
“There’s a loan,” I said. “A HELOC. Forty-two thousand dollars against the house, and my name is on it. I never signed for that.”
Silence.
Then Mom’s voice flattened into the particular calm she used whenever she had already selected the version of reality she intended to defend.
“Your father handles all of that. You’ll have to ask him.”
“Is he there?”
“He’s not comfortable discussing this right now.”
“Mom, somebody forged my signature.”
“Don’t be dramatic, Elena. Nobody forged anything. You probably don’t remember signing it. You sign so many things.”
I ended the call before anger could make me say something I would later feel obligated to apologize for. That realization almost made me laugh. Usually, in my family, I apologized first and figured out what I had supposedly done wrong afterward.
Before the Financial Crimes Unit ever contacted me, I called First Union myself.
Their fraud department put me on hold long enough for the same forty seconds of saxophone music to repeat eleven times. Finally, a man named Tom Bellanger answered. He introduced himself as a fraud investigator, opened the file while I spoke, and then asked a question so calmly that it took the air out of my chest.
“Ma’am, I’m showing an eighteen-month payment history with no delinquencies until sixty days ago. Are you certain you didn’t authorize this and simply forget the terms?”
“Yes.”
I told him I hadn’t lived at my parents’ address in three years. I had not received a single statement. Later, we discovered why. The account had been switched to paperless delivery using an email address that was not mine.
Tom said that mattered.
Then he explained something worse.
Family fraud was often harder to prove than fraud committed by strangers because the usual warning signs barely existed. A stranger using your identity might shop somewhere unfamiliar, log in from another state, or make purchases completely outside your habits. A family member already knows your birthday, your address, your employer, your mother’s maiden name, and half the answers a bank might use to verify you.
The system had not failed to notice something obvious.
It had been handed information designed to look ordinary.
“I can open an internal investigation,” Tom said. “But it runs on our timeline. And I need to be clear, internal investigations often end with account closure. If you want this treated as a crime, you need a police report. We follow law enforcement’s lead, not the other way around.”
That was when I finally understood what the next several months might require.
The bank wanted police involvement.
The police wanted documentation.
My attorney wanted both before making the next move.
No institution was going to gather all the pieces for me.
If I wanted the truth attached permanently to my own name, I was going to have to become the connection between every office, every file, every skeptical stranger, and every signature that somebody else had decided they were entitled to use.
One phone call at a time.
One document at a time.
One fact at a time.
Part 2….
The following Tuesday, my phone rang.
“Ms. Elena? Detective Renee Okafor, Financial Crimes Unit.”
Something in her voice immediately made me sit straighter. She sounded calm without sounding detached, serious without trying to frighten me.
“I have your case file,” she said.
I closed my office door.
Detective Okafor had been working financial crimes for fourteen years. She didn’t waste time pretending this would be simple.
“I want to be straight with you before we go any further,” she said. “Forgery and identity theft cases involving family members are some of the hardest cases to prosecute.”
My fingers tightened around the phone.
“Because there isn’t enough evidence?”
“Not necessarily.”
She paused.
“Sometimes the evidence is strong. The problem is that juries, and occasionally prosecutors, have trouble believing relatives would do something like this to each other.”
I looked at the copy of the four-page power of attorney lying on my desk.
My signature.
Not my document.
My parents’ address.
My income.
My Social Security number.
Eighteen months of payments I had never known existed.
For years, I had been told I was dramatic whenever I objected and forgetful whenever somebody needed my version of events to disappear. Now I understood that the same story could follow me into a courtroom unless I could replace every argument with proof.
Detective Okafor continued.
“So I need you to help me build this carefully.”
“How carefully?”
Her answer came without hesitation.
“Something that doesn’t leave room for that doubt.”
𝑻𝒉𝒆 𝒏𝒆𝒙𝒕 𝒑𝒂𝒓𝒕 𝒊𝒔 𝒄𝒐𝒎𝒊𝒏𝒈 👇