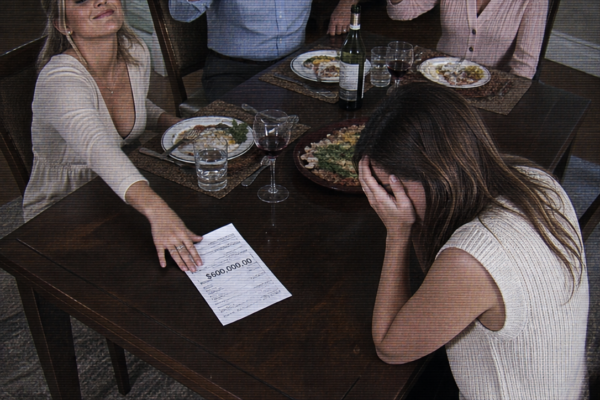
My boyfriend’s father sneered “street garbage” across a silent dinner table while twenty
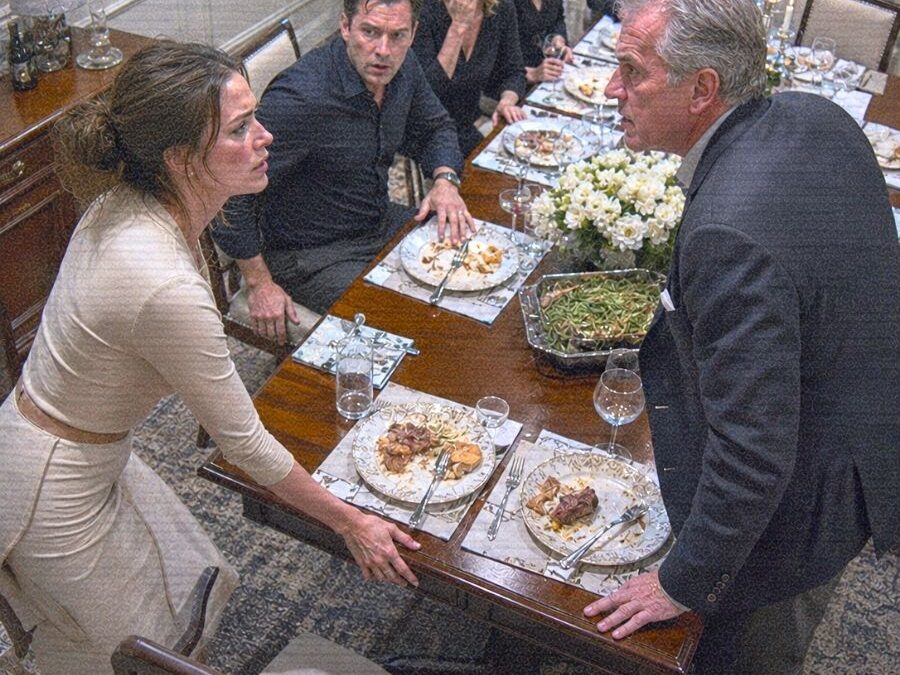
The Offer Vanished And His Company Began Bleeding Immediately Afterward
Evan drove home in silence.
Streetlights passed across the windshield while I thought about my mother and the motel room Silas had tried to weaponize. I searched myself for humiliation and found none.
What I felt was clarity.
Eventually Evan pulled into our driveway and left the engine running.
“I didn’t know,” he said.
“You couldn’t.”
“Your firm was trying to buy his company.”
“We had made an offer.”
“And you withdrew it because of tonight.”
“Yes.”
He stared toward the porch.
Then he said something I would remember long after the acquisition itself.
“Do what you would have done if you’d never met me.”
“Evan.”
“I mean it. Don’t protect him because he’s my father. I’ve spent years letting comments go because fighting him always seemed harder than ignoring him.”
He turned toward me.
“He needs to learn that some consequences can’t be talked away.”
Inside, I reviewed what counsel had done after receiving my message.
The withdrawal was complete. Records were preserved. Our indication of interest had been formally terminated.
I genuinely believed the deal was probably dead.
I had not withdrawn to manipulate Silas into accepting worse terms later. I withdrew because I no longer wanted my investors partnering with a man whose first instinct, when confronted by someone he considered socially beneath him, was humiliation.
The next morning, Margaret did not call begging us back.
The board did something smarter.
They reopened talks with the losing bidders.
They approached lenders seeking additional time.
They ordered deeper diligence.
And they asked Silas how much of his own money he was willing to invest to keep the company independent.
His answer was none.
He argued that using personal capital would be irresponsible because the liquidity crisis was temporary. He insisted buyers would eventually overlook one “uncomfortable dinner” and return.
That answer changed how several directors saw him.
Silas had spent months talking about protecting the company he built. Asked to risk his own fortune beside everyone else’s, he declined.
Meanwhile, the alternatives were ugly.
A strategic buyer remained interested at approximately $90 million below our original offer, but its proposal involved longer regulatory review and closing overlapping terminals.
A distressed investment fund offered roughly $160 million less and planned deeper layoffs and property sales.
Neither solved the debt deadline cleanly.
Then the deeper diligence results arrived.
Approximately $50 million in deferred fleet maintenance.
An insurance reserve shortfall of about $27 million.
Two major customer contracts representing close to ten percent of annual revenue were heading toward competitive rebid.
None of it was fraud.
That almost made it worse.
These were operational facts accumulated slowly under Silas’s leadership while he continued behaving publicly as though the company’s only problem was that everyone else lacked his confidence.
Three weeks after the dinner, Margaret called me.
“Would you reconsider?”
I said nothing for a moment.
“I’ll take it back to the committee,” she continued. “If there’s any appetite left on your side.”
“We’d have to rebuild the valuation.”
“I understand.”
“The old offer is gone.”
“I understand that too.”
“And if we come back, the terms may not resemble what Silas rejected.”
Margaret exhaled.
“Frankly, Claire, I think several people around that board table are counting on that.”
My team spent the next week rebuilding everything.
Not from anger.
From facts.
The new diligence supported a lower valuation. We documented every adjustment line by line.
The revised enterprise value came in just over $1.18 billion, approximately $75 million below our original proposal.
Deferred maintenance reduced value.
The insurance reserve gap reduced value.
Customer renewal risk reduced value.
We also added something our original analysis had not quantified sufficiently: founder transition risk.
Silas had demonstrated that his need for personal control could directly threaten transactional certainty, customer confidence, and board governance.
His behavior had become financially measurable.
Our new conditions were uncompromising.
No executive chairman role.
No hiring veto.
No strategic approval authority.
No corporate aircraft access.
No hidden avenue back into operational control.
In exchange, we increased committed liquidity and modernization funding to $175 million, retained employment protections below the executive level, required a genuinely independent compliance committee, and mandated a formal search for Silas’s replacement as chief executive.
Margaret presented the package to the board.
She later told me Silas stood before she finished.
“She’s using the company to settle a personal score!”
Margaret looked at him.
“Then explain fifty million dollars of deferred maintenance without mentioning dinner.”
He could not.
“Explain the reserve shortfall.”
He could not.
“Explain the customer concentration risk.”
Again, nothing.
Those numbers existed before Silas ever insulted me.
The dinner had not created them.
It had merely caused us to stop giving him the benefit of softer assumptions.
The board voted six to one to recommend our revised transaction.
Silas cast the only dissenting vote.
He still believed that mattered more than it did.
He owned close to thirty percent of the shares personally. A family trust controlled another substantial block, but an independent corporate trustee, not Silas, held voting authority over the trust shares.
Neither Evan nor I contacted the trustee.
Nobody at my firm needed to.
Institutional shareholders and the trustee received the same fairness analysis, financing commitments, and side-by-side comparisons of the competing offers.
The decision was arithmetic now.
Approximately sixty-eight percent of shares voted in favor.
When the count was announced, Silas stared across the boardroom.
“This is my company.”
Margaret closed her binder.
“It’s a corporation, Silas. Not an inheritance with employees.”
The transaction would be financed with hundreds of millions in equity from our funds and co-investors and nearly $700 million in committed senior financing.
There was no dramatic personal check from me.
No hostile midnight takeover.
Just documents.
Votes.
Financing commitments.
Legal approvals.
Closing conditions.
And one founder slowly discovering that the corporation he had built had never legally been an extension of his personality.
Closing was scheduled nine weeks after the dinner.
Silas signed eventually.
People close to him told us he still believed some compromise would restore his authority afterward.
He thought the company’s name on the trucks meant something.
He thought history would outweigh ownership.
He thought signatures were paperwork.
He was about to discover exactly what signatures can do.